
A free-to-spend crypto card with a narrow top-up lane and a thin safety margin
 Available in US
VaultLeap is a virtual Visa card that spends a USDC balance you move across the dashboard yourself. It charges nothing to hold and nothing per purchase, and it advertises a 27-country footprint centred on the United States and Latin America. That combination — no monthly fee, no foreign transaction fee, no currency markup — is genuinely rare, and it is why the card keeps coming up in searches from people who want a plain spending card without a bank in their country.
I scored it 6.0 out of 10. The cost side of that score is the strongest part; the top-up, the complaint record and the sheer narrowness of what the card will do drag the rest down. It is not a bad card. It is a card with one job, one funding rail and one currency, and the person it suits has to be comfortable with all three. Read on if you are deciding between it and something else, or if you are simply trying to work out whether the zero fees survive contact with a real shop.
The conditions described here are current as of October 28, 2026.
Verdict: 6.0 out of 10
My score breaks into five parts, and the spread between them is the story. Cost is the outlier at the top; everything else clusters in the middle.
| Criterion | Mark | Why |
|---|---|---|
| Who can get it | 5 / 10 | Advertised for 27 countries — the United States, Latin America and Ghana — but the cardholder agreement says it is issued under U.S. law and “not directly marketed outside the U.S.” |
| Cost | 9 / 10 | $0 a month, $0 a year, $0 per purchase, free closure, 0% international fee, no FX markup. The conversion still carries roughly 0.5% of partner pass-through fees, and the issuance fee is not disclosed. |
| Top-up options | 5 / 10 | USDC only, moved by hand from your VaultLeap balance through Dashboard → Card → Add Funds. Other coins and networks are not stated. You pay the gas. |
| Reliability and complaints | 5 / 10 | Issued by Lead Bank, programme managed by Bridge Ventures LLC. Trustpilot shows 3.4 from 34 reviews, with reports of account blocks in 2026 and funds not landing. |
| Everyday use | 5 / 10 | A virtual Visa in minutes, Apple Pay and Google Pay supported. No plastic, no ATM. |
| Total | 6.0 / 10 | A cheap card with a narrow lane to feed it. |
Who it suits: someone in the US or Latin America who already holds USDC, pays mostly online, and wants a card with no monthly fee and no foreign transaction markup. Who it does not: anyone who needs cash from an ATM, anyone who wants a physical card in the post, anyone who spends in a currency other than the US dollar, and anyone who wants to load from a bank account rather than from crypto they already own.
Let me be precise about one thing that readers often get wrong. VaultLeap is not a bank. It is a card front-end. The card is issued by Lead Bank, a Missouri state-chartered bank; the programme is managed by Bridge Ventures LLC, a Delaware money transmitter; the company operating the platform is Klydo Inc., a California S corporation. The cardholder agreement is written as a prepaid debit Visa card agreement, which matters later when we get to what happens if your account is frozen.
Will they give you the card?
Yes, if you are in the right place and over 18 — and the “right place” is stated more loosely than you might expect.
VaultLeap advertises the card for 27 countries, but it does not publish the list on the page. What it does publish is the starting set: the United States, Latin America — Argentina, Colombia, Mexico, Brazil, Peru, Bolivia, Guatemala, Dominican Republic, Ecuador, Costa Rica, El Salvador, Honduras, Panama, Paraguay, Uruguay — and Ghana. That is fewer than 27 countries once you count them, which means the marketing claim covers more ground than the detail does. If you live somewhere not named in that run of countries, you will have to ask.
More important than the count is this line from the cardholder agreement: the card is issued under U.S. law and is “not directly marketed outside the U.S.” That is not the same as “not available outside the U.S.” — many Latin American residents are issued cards under US law without the card being marketed to them. But it is the reason I have not given this category mark a higher score for access. You are being onboarded by a US-regulated structure, and if you are in Ghana or anywhere else outside the Americas, the practical answer is not on the page.
One more condition: you must be at or above the age of majority. The public pages do not give a number, so the age of majority in your country is the threshold that applies. For an 18-year-old in most of Europe and the Americas, that line is no obstacle at all.
How to get it
The sign-up is short, which is the appealing part. The catch is that the public pages do not tell you everything you will be asked for.
You need to be 18+ and complete identity verification. The card is requested from the dashboard “once your account is verified”. Beyond that, the public pages are silent: which documents are accepted, and whether proof of address is required, are not stated. If you are someone for whom that matters — an applicant without a utility bill, or in a country where the accepted documents differ — you will only find out by going through verification and reading the rejection message.
What you get at the end is a virtual Visa debit card. In the legal text it is a “Prepaid Debit Visa Card”, denominated in US dollars, and the page says it is issued in minutes. There is no physical version described anywhere on the public pages. A virtual card is genuinely fine for online spending, and if you use a phone it is fine in shops too, because you can push it into Apple Pay or Google Pay. If you have ever wanted a card that works on a terminal that taps a physical strip, that is not this card.
Replacement, at least, costs nothing: the page states plainly that “there is no fee for replacing your Card”. So a lost or reissued virtual card does not hit your wallet — the problem is what losing it means if your phone goes with it, which I come back to in the risks section.
Verification tiers are not stated, so I cannot tell you whether heavier use triggers a second round of checks. What every regulated onboarding does have is the risk assessment described in the background below, and that is where the freezes people complain about come from.
What it really costs: the Fees
The cost picture is the strongest thing about this card, and it is the reason I scored it 9 out of 10 on price. Here is every fee the card’s own pages state.
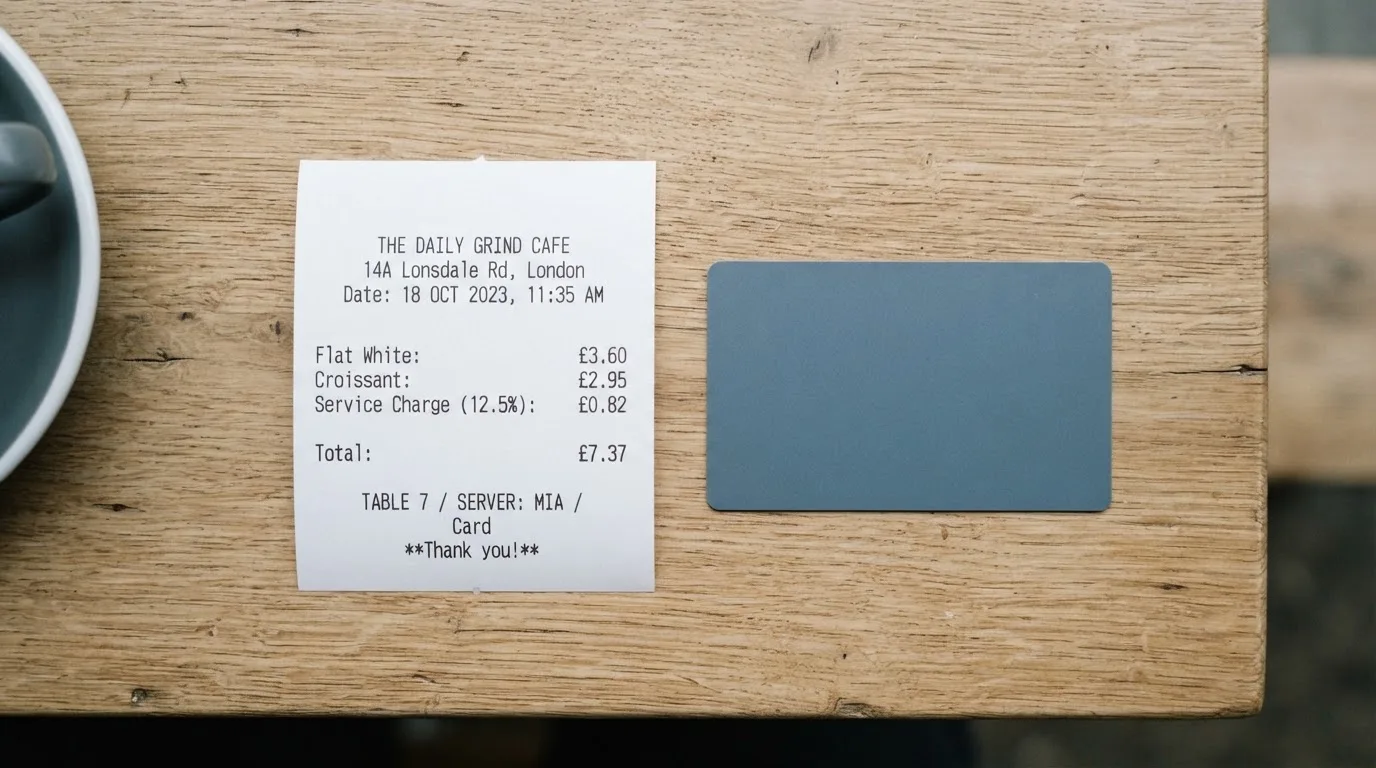
| Fee or limit | What the card states |
|---|---|
| Monthly fee | $0 |
| Annual fee | $0 |
| Per purchase | $0 |
| Closure | Free |
| International transaction fee | 0% |
| FX markup | None — “No FX markup” |
| Conversion | Carries roughly 0.5% partner pass-through fees |
| Issuance fee | Not stated |
| ATM withdrawal | Unavailable (“n/a”) |
| ATM balance inquiry | Unavailable (“n/a”) |
| Maximum load per transaction | $2,000.00 |
| Other limits | May be set by the bank |
Three of those rows deserve a paragraph rather than a table line.
The 0.5% on conversion is the fee you will actually meet. It is not a VaultLeap markup; it is partner pass-through fees that ride along when your balance is converted. It is small, it is disclosed, and it is the price of the zero-fee headline. If you are spending in dollars, you may not meet it at all.
The ATM rows are the ones that hurt. No cash, no balance check at a machine. In a country where cash still matters — and in much of Latin America it does — this removes the card from serious daily use and turns it into an online and contactless-wallet card. There is no workaround I can point you to; the feature is simply absent.
The $2,000 per-transaction cap is the ceiling on how fast you can feed it. You can load two thousand dollars’ worth in one go and no more. That is fine for day-to-day spending. It is a real constraint if you are, say, settling a rent payment or a large invoice.
Let me put three everyday payments through it, so you can see which of those lines you actually meet.
A $60 subscription in dollars. Nothing. Monthly fee $0, per purchase $0, no FX because you are paying in the card’s own currency. This is the payment VaultLeap is built for.
A €45 dinner in Europe. No international transaction fee, no FX markup, and the card says foreign purchases go through at the Visa network rate. You pay the roughly 0.5% partner pass-through. So the cost is a fraction of a percent of €45, not the three or four percent a typical bank card charges on a foreign purchase. This is where the card quietly earns its keep — provided the shop accepts a US-issued prepaid Visa, which not all of them do.
A $40 taxi paid by tapping a phone. Also $0 in fees, no ATM involved, no foreign conversion. But the money has to already be sitting in the card balance as USDC-converted dollars, which brings us to how you get it there.
Two structural costs sit outside the table because they belong to the account rather than the card. VaultLeap offers account plans — Standard, Pro at $14.99 a month or $144 a year, and a Zero tier relating to transfer fees — but these are platform plans, and the card product itself is a single product with no card tiers. And the blockchain fee for moving your own funds is not a card fee at all; it is charged by the network you use, which is a category-wide fact rather than a VaultLeap charge.
How to Top up
This is where the card’s simplicity becomes its limit, and I would rather you heard it from me than discovered it at checkout.
Topping up is manual, in USDC only, from your existing VaultLeap balance. The path is Dashboard → Card → Add Funds, and the USDC moves to a card wallet that runs on Bridge. You do it by hand. There is no schedule, no autopay, no bank transfer into the card, and no card-network top-up.
The deposit fee and the minimum top-up are not stated on the public pages. What is stated is that you pay the blockchain gas yourself — the network charges for your transfer, not the card provider. On a busy network that is a small but real cost; on a cheap one it is nearly nothing. Either way it comes out of your own pocket and it is not one of the card’s free fees.
What this means practically: VaultLeap is not a way to get from your bank account to a card. It is a way to get from USDC you already hold to a card. If your crypto is on a hardware wallet, in a different exchange, or in a different coin, you have work to do before this card is of any use to you. The public pages are also not stated on whether other coins or other networks are supported — the honest reading is that USDC is the documented path and nothing beyond it is promised.
Money coming back out, so you know what happens if you change your mind: closing the account is free, and the remaining fiat balance goes to your platform wallet as stablecoins. The bank may refuse balances under $1.00. From the account you can withdraw to any supported USD or EUR bank account.
One warning worth repeating, because it belongs to this section and not the safety section: blockchain transfers are irreversible. Send on a network the provider does not support, or to an address belonging to a different network, and the money may simply be gone, or recoverable only through a manual support request with no guarantee. Circle stopped supporting USDC on Tron in February 2024, so “USDC over TRC20” is not a native option on any of these platforms. Check the network before you confirm anything.
Paying with it every day
Everyday use is competent and narrow. The card works where Visa works online, and it lives in your phone’s wallet.
Apple Pay: yes. Google Pay: yes. That covers most in-person spending for anyone who carries a phone. Adding it is the standard flow — you add the card to the wallet app and confirm through the dashboard. Each wallet payment uses a device-specific number and a one-time security code rather than your actual card number, which is a meaningful protection if your card details leak.
There is no plastic, so a shop that insists on a physical card or a signature is not an option. There is no ATM. And the blocked merchant categories are not stated — which means you do not know from the public pages whether gambling, adult content, fuel or travel will be declined by policy. That is a real gap, and if any of those matter to you it is worth asking before you rely on the card.
On rewards, the honest position is that no cashback is stated on the card page. There is a separate “Points & Rewards” help category whose contents I did not read, so I am not going to claim there is nothing there — only that the card itself does not advertise a cashback rate. Assume zero unless you find otherwise.
The app is on the App Store and Google Play; the store ratings I did not read.
Disputes and errors are handled through a route that at least exists. You file through Dashboard → Support → File a Ticket → Dispute a Charge. You are asked to report errors within 60 days. The bank then decides within 10 business days, stretching to 45 days — and up to 90 days for a new card, a point-of-sale purchase or a foreign purchase. Unauthorized payments are to be reported within 2 business days, with liability capped at $50 and, later, up to $500. Those are standard-shaped numbers for a US-issued card, and the two-business-day line is the one to bookmark.
One structural feature to understand before you are surprised by it. Because this is a prepaid card drawing on a stored balance, the money comes off the card, not off your bank account at the moment of purchase. That means the balance simply cannot go below zero — you cannot overdraw. The cost of that safety is that declined payments and holds behave differently: a declined online authorisation can leave a hold on your funds for days, typically up to seven.
What can go wrong
I found no official incident. What I found instead was a pattern in user reports, and I would rather show you that pattern than the marketing.
On Trustpilot the card sits at 3.4 out of 5 from 34 reviews, as read on 21 October 2026. That is a small sample, and I want to be honest about what a small sample means: it is a signal, not a verdict. But the themes repeat, and they are the three you would least like to meet:
- Accounts suspended or blocked without a clear reason, reported in January 2026 and again across June to August 2026.
- Funds not credited or not returned, reported in October 2025 and June 2026.
- Poor or unclear communication from support, which is the thread running through the other two.
The most recent review I read, dated 12 October 2026, acknowledges problems with card issuance itself. This is user-reported and not confirmed by the card, but it is recent and it is about the one thing you cannot do without: getting the card in the first place.
Here is my own read of why this happens, and it is not mysterious. This is a US-regulated onboarding process screening applicants across multiple jurisdictions, and the law obliges it to check identity, sanctions status and risk continuously. When that process cannot be completed, the institution is required to hold off or close the relationship — which is exactly why accounts freeze and why documents get demanded. From the inside that is compliance. From your side it is your money stopped for a reason nobody explains. The complaints describe the second experience, not a misconduct finding, and I would not read them as proof that the card is unsafe. I would read them as proof that the friction is real.
Support, at least, is bilingual: email in English and Spanish, plus a Support tab with tickets. No official news or announcements on this are not stated, which means I cannot tell you what the company has said in response.
Three structural risks that are not about the company’s conduct:
Your funds are not bank deposits. The terms say VaultLeap “does not hold customer funds” and the wallet is self-custodial, which is a genuine architectural strength — the crypto stays with you rather than on someone’s balance sheet. But that also means the funds are not FDIC insured. Self-custody cuts both ways: it removes the custodian’s hack risk, and it moves key-loss, phishing and clipboard-swap risk entirely onto you. Anyone who obtains your seed phrase can restore the wallet and spend it, and blockchain transfers have no built-in recovery.
You can freeze the card yourself. Dashboard → Card → Freeze. That is the single most useful control on this card and you should know where it is before you need it. Spending limits and tokenisation give you further levers — and note that an issuer can also restrict a tokenised number, blocking it on magnetic stripe, phone or website use.
The card can be wound down. Platforms behind crypto cards do close. Visa terminated its global agreements with FTX in November 2022 and the FTX US debit card was wound down by its issuer; Visa suspended WaveCrest in Europe in 2018, closing every WaveCrest-issued Visa programme in the region. Shutdowns usually follow a shape: a notice period, then loading and spending stop, then you are asked to withdraw what is left. A secondary source reported one 2026 closure with new loads ending 8 July 2026 and spending stopping 8 August 2026 — single source, unconfirmed, and I mention it only to show the pattern is current.
Two things that are outside your control and worth planning around. Merchants can look up the issuing institution and country from the card’s first six or eight digits and apply extra scrutiny when that differs from your billing address — which is why a US-issued card can look “foreign” to a shop in another country, and why some decline prepaid or foreign-issued cards outright. And address verification, which compares the numeric parts of the billing address you type against issuer records, is mainly offered in the US, Canada and the UK and is generally unavailable for foreign-issued cards, which can cause declines on their own.
What to take instead
I compared VaultLeap against three other crypto cards. None of them is dramatically better; they trade differently.
| Card | Score | Access | Fees | How it loads | Rewards |
|---|---|---|---|---|---|
| VaultLeap | 6.0 / 10 | Advertised for 27 countries; US and Latin America named; issued under U.S. law | $0 monthly, $0 annual, $0 per purchase; ~0.5% on conversion; no FX markup | Manual USDC from your own balance | None stated |
| Stella | 6.5 / 10 | Countries not stated; US and European users routed through affiliates; sanctions terms apply | Not stated on the public pages | Crypto deposit auto-tops the card; custodial in-app wallet | None stated; a separate earn product |
| Whop Cards | 5.2 / 10 | Consumers in 31 US states; 41 for businesses; 18 named countries unsupported | Page says “No extra fees”; no amounts listed | Spends a Whop balance, usable as soon as a payment arrives; stablecoin-collateral backing | 5% cashback at select merchants, currently Uber |
| UniFi Card | 4.7 / 10 | Not confirmed from official pages; app routes to Philippines, Mexico, eurozone, with Colombia, Brazil and UK in release notes | “Fees may apply” — nothing published | ACH, wire, SEPA, SPEI, or get paid to a USDC wallet | “3% rewards on balances” per the listing; card cashback not stated |
Stella scores slightly higher than VaultLeap and is the nearest comparison. It has both virtual and physical cards, works at what it calls over 40 million Visa merchants globally, and it loads more easily — crypto goes in and the card tops up automatically, custodial in-app wallet rather than a manual USDC move. What it gives up is disclosure: the official site does not state countries, and fees are “described under this User Agreement and/or on the App”. If you want a physical card and easy top-ups, and you are willing to read the app’s fee section yourself, Stella is a fair pick. Its terms bar users under economic sanctions programmes, so check that first.
Whop Cards is the most transparent of the three on access — it names the 31 US states it covers for consumers and the 18 countries it does not support — but it is the most limited in reach, and it is built around a Whop balance rather than around holding your own crypto. Its 5% cashback at select merchants is real-sounding and, notably, is the only rewards rate any of these cards states plainly. Payout currency and conditions are not stated.
UniFi Card is worth a look only if you live in one of the corridors its app actually serves, because access is not confirmed on its official pages. It is also the only card here that accepts ordinary bank rails — ACH, wire, SEPA, SPEI — which is a genuine advantage if you do not want to hold crypto at all. Its fees are the least published of the four.
The honest summary: VaultLeap is the cheapest to hold and the clearest on costs, and the least flexible on funding and on the cards you will be offered. Pick it for the price and the zero foreign transaction fee. Pick Stella for a physical card and easier funding. Pick Whop if you are in a named US state and the merchant cashback matters. Pick UniFi if bank transfers matter more than fees.
Who I would recommend it to
I would recommend VaultLeap to someone specific: a resident of the US or Latin America who already holds USDC, pays most of their bills online or by phone, and has been put off by a 3% foreign transaction fee. For that person this is a good card. Free to hold, free to spend, free to close, no currency markup, and a card number in your wallet within minutes.
I would not recommend it to someone who needs cash, who wants a physical card, who spends in euros or pounds from a US dollar balance without wanting a conversion charge, who expects to load from a bank account, or who is uneasy about a platform that can freeze an account and take a while to explain itself. The complaint record — small sample, repeated themes, and a recent review about issuance — is not a reason to walk away on its own, but it is a reason to keep only what you can afford to have frozen for a fortnight.
And I would check three things before you commit. Ask which countries are actually covered, since the page names fewer than it claims. Ask what the issuance fee is, since it is not stated. And read the tokenisation controls, so you know whether your card can be restricted on a given channel before you are standing at a till. Those three questions cost you an email and would cost you a great deal more to learn by accident.
Frequently asked questions
What is VaultLeap card?
VaultLeap is a virtual Visa debit card that spends USDC you hold on its platform. The company operating it is Klydo Inc., a California S corporation; the card is issued by Lead Bank, a Missouri state-chartered bank; and the programme is managed by Bridge Ventures LLC, a Delaware licensed money transmitter. It is a card front-end, not a bank you hold an account at.
How does VaultLeap card work?
You convert or hold crypto on the platform, then move USDC manually from your VaultLeap balance to the card wallet through Dashboard → Card → Add Funds. From there it behaves as a stored-balance prepaid card: purchases draw down that balance, so it cannot overdraw, and foreign purchases go through at the Visa network rate. Card payments can be made online or through Apple Pay and Google Pay.
Is VaultLeap a bank?
No. The issuer is a bank — Lead Bank — but VaultLeap itself is not one. The cardholder agreement describes a prepaid debit Visa card issued under U.S. law, and the public pages say it is “not directly marketed outside the U.S.” Your funds are explicitly not held by the platform, and they are not FDIC insured.
Who owns VaultLeap?
The platform is operated by Klydo Inc., a California S corporation. Bridge Ventures LLC, a Delaware company and licensed money transmitter, is the programme manager. The issuing institution is Lead Bank. None of this is hidden, but it is worth understanding that the brand you see is the marketing layer over a bank-issued card programme.
Who can apply for VaultLeap card?
You need to be at or above the age of majority — prepaid cards are generally for adults — and complete identity verification. VaultLeap advertises 27 countries, naming the United States, Latin America and Ghana as starting data, but does not publish the full list on the page. Where you live is the first thing to check, because the card is issued under U.S. law.
Does VaultLeap card require KYC?
Yes, identity verification is required, and the card is requested from the dashboard only once your account is verified. Which documents are accepted, and whether proof of address is needed, are not stated on the public pages. Expect the standard regulated checks: identity, sanctions screening and ongoing transaction monitoring.
Is VaultLeap card free?
Mostly, yes. Monthly fee $0, annual fee $0, per purchase $0, closure free, international transaction fee 0%, and no FX markup. The two costs to know about are roughly 0.5% of partner pass-through fees on conversion, and the blockchain gas you pay when moving your own USDC. The issuance fee is not stated.
How do I top up the VaultLeap card?
Manually, in USDC, from your VaultLeap balance via Dashboard → Card → Add Funds. The maximum load per transaction is $2,000.00. Other coins and networks are not stated as supported, and the deposit fee and minimum are not published. Remember blockchain transfers are irreversible, so check the network carefully before confirming.
Can I use VaultLeap card in my country and at ATMs?
You can use the card wherever Visa is accepted online, and in shops through Apple Pay or Google Pay — though some merchants decline prepaid or foreign-issued cards. ATMs are the exception: ATM withdrawals and balance inquiries are listed as unavailable, so no cash. There is also no physical card, only the virtual one.
Is VaultLeap card safe?
There is no official incident I could find, but I would weigh the user reports. Trustpilot shows 3.4 from 34 reviews, with repeated themes of accounts suspended without clear reason in 2026 and funds not credited or returned. The architecture has real strengths — self-custodial funds, instant freeze, tokenised mobile wallets — but the funds are not FDIC insured, and key loss and fraud risk sit with you.
Highest-scored app and neobank cards – cryptocardbest.com
Content created by the «cryptocardbest.com» team